Burst Pipe Insurance Claims in Kent, WA
Last updated: October 2026
What is covered, what is not, and the Washington State law that protects your right to choose your own restoration contractor. We bill your carrier directly.
What do I need to know first?
What a covered burst pipe claim in Kent typically looks like:
| Scenario | Typical Kent range | Who pays |
|---|---|---|
| Single room (bathroom / kitchen) | $1,500 – $4,500 | Insurer, minus deductible |
| Multi-room / hallway spread | $4,500 – $9,000 | Insurer, minus deductible |
| Crawlspace flooding (pipe cause) | $2,500 – $8,000 | Insurer, minus deductible |
| Multi-room + mold remediation | $8,000 – $18,000 | Insurer if reported promptly |
| Pipe repair or repipe | $300 – $14,000 | Homeowner |
Kent, WA ranges through the WA Restore Pro contractor network, 2025–2026.
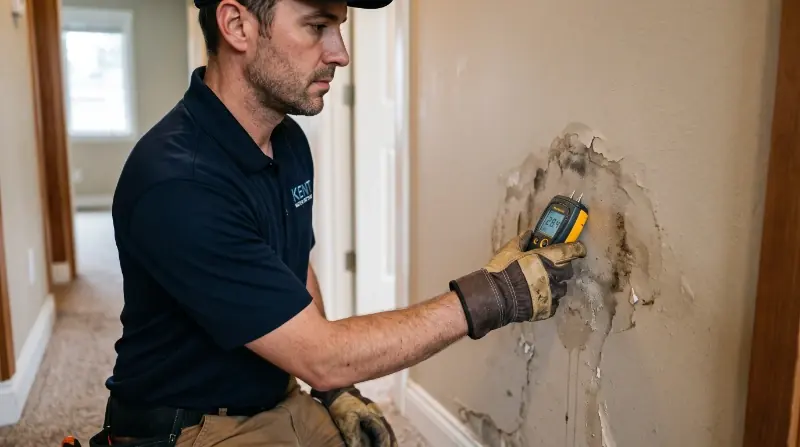
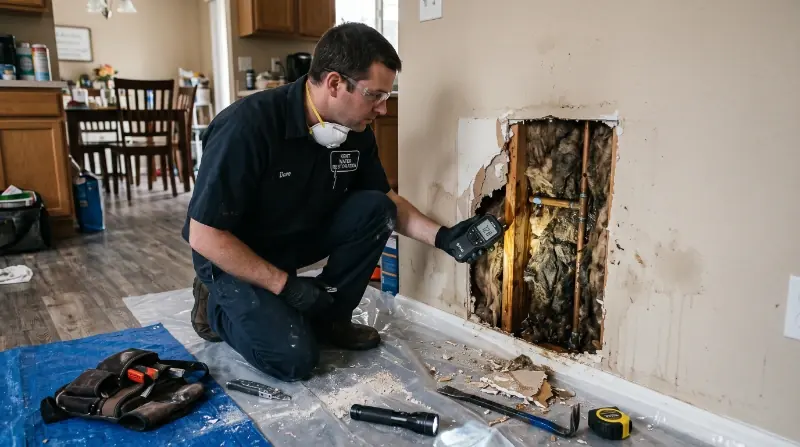
Most standard homeowner policies in Kent, WA cover burst pipe restoration as sudden and accidental water damage. This includes water extraction, structural drying, and repairs to damaged drywall, flooring, and insulation. The coverage does not apply to gradual leaks, deferred maintenance, or external flooding from the Green River, which requires a separate NFIP policy. We handle direct billing to all major carriers and prepare the full documentation package your adjuster needs. You have the legal right under Washington State law to choose your own contractor.
What does a homeowner policy cover for a burst pipe in Kent?
The Washington State Office of the Insurance Commissioner states that homeowners insurance generally covers sudden leaks but may not cover gradual leaks. A burst pipe that fails suddenly due to freezing, corrosion failure, or a supply line blowout qualifies as a sudden and accidental loss under most standard HO-3 and HO-5 policies.
Standard coverage for a sudden burst pipe in Kent typically includes:
- Emergency water extraction costs
- Structural drying using commercial equipment
- Repair or replacement of damaged drywall, insulation, and flooring
- Repair or replacement of cabinets, trim, and built-ins that absorbed water
- Personal property damaged by the water, under Coverage C
- Additional living expenses if your home cannot be occupied during repairs, under Coverage D
- Mold remediation if mold resulted directly from the covered burst pipe event
Your deductible applies. Coverage limits vary by policy. Reading your specific declarations page will tell you your dwelling coverage limit, your deductible, and whether you have any water backup or sewer backup endorsements that affect related claims.
What is not covered on a Kent burst pipe claim?
Gradual Leaks and Deferred Maintenance
Insurance companies look for signs of long-term water intrusion when they inspect a loss. If staining patterns, mineral deposits, or mold behind walls suggest a pipe has been leaking slowly for an extended period, the carrier may argue the damage is not sudden and accidental and deny part or all of the claim. This is one of the most commonly disputed issues in water damage claims, according to coverage attorneys in Washington State.
If an adjuster is classifying your loss as gradual rather than sudden, get a written opinion from a licensed plumber and a restoration professional documenting the evidence that the failure was sudden. Our documentation is specifically organized to support this distinction.
Green River Flooding and External Water
Standard homeowner policies specifically exclude flooding from external water sources. If the Green River overtops its banks, if a storm drain backs up onto your property from outside, or if surface water enters through your foundation during heavy rainfall, that is flood damage, not a covered pipe loss.
The December 2025 atmospheric river event that caused the Green River to jump its banks near West Valley Highway, close Frager Road at West Meeker Street, and close Russell Road at Veterans Drive created both types of claims simultaneously in some Kent homes. A pipe inside the house that burst from the stress of rising groundwater may be covered. Water that entered from outside is not, without NFIP coverage.
If your property is in a FEMA-designated flood zone along the Green River corridor, including the Riverview neighborhood and properties near 78th Avenue South, your mortgage lender may already require NFIP flood insurance. FEMA's flood map service center at msc.fema.gov allows you to check your property's flood zone designation by address.
Sewer Backup
Sewage backing up through floor drains or toilets is excluded from most standard policies unless you purchased a water backup or sewer backup endorsement. If you have older clay sewer lines, particularly in West Hill neighborhoods where tree roots are a documented issue, this endorsement is worth adding to your policy before the next problem occurs.
What are your rights as a Kent homeowner during a water damage claim?
Washington State law gives homeowners specific rights when filing water damage claims that many people do not know about.
Right to Choose Your Own Contractor
You are not required to use a restoration company from your insurance carrier's preferred vendor program. That list exists because carriers have negotiated rates with those companies, not because those companies are necessarily the best option for you. The Washington State Insurance Commissioner confirms you have the right to select your own contractor.
Right to Independent Inspection
If your carrier's adjuster produces a scope of loss that you believe undervalues the damage, you can hire a public adjuster or request an independent inspection. We can provide additional documentation and connect you with licensed Washington State public adjusters who specialize in residential water claims.
Right to File a Complaint
If you believe your carrier is handling your claim in bad faith, the Washington State Office of the Insurance Commissioner accepts consumer complaints and investigates claims handling practices. Their complaint portal is at insurance.wa.gov.
How does direct insurance billing work for Kent burst pipe restoration?
We work with all major carriers serving Kent homeowners, including Safeco, State Farm, PEMCO, Allstate, Farmers, Nationwide, and others. Our documentation package includes everything your adjuster needs to process the claim:
- Photographs of all affected areas, taken before, during, and after remediation
- Moisture readings with timestamps covering the full drying period
- Equipment placement logs showing dehumidifier and air mover deployment
- A line-by-line estimate in Xactimate format, which is the standard estimating software most carriers use
- A written scope narrative explaining what happened, what was affected, and why each line item is necessary
- IICRC S500 compliance documentation for the drying process
We submit directly to your adjuster and respond to any requests for additional documentation. Your job is to let us in and make a phone call to open the claim. We handle the rest.
Burst pipe insurance questions
Does homeowner insurance cover burst pipe restoration in Kent, WA?
Most standard homeowner policies cover sudden and accidental burst pipe damage. The Washington State Office of the Insurance Commissioner confirms that policies generally cover sudden leaks. Coverage typically includes extraction, drying, and repair of damaged structural materials and personal property. It does not cover gradual leaks, flood from external sources, or deferred maintenance.
Can I choose my own restoration company for a burst pipe claim in Kent?
Yes. Washington State law gives homeowners the right to choose their own contractor. Your insurance company cannot require you to use their preferred vendor list. If an adjuster suggests you must use a specific company, that instruction is worth questioning and documenting in writing.
What is the difference between burst pipe coverage and flood coverage in Kent?
Burst pipe damage from a pipe inside your home is covered as sudden and accidental under standard homeowner policies. Flood damage from external water sources, including the Green River or storm water accumulation, requires a separate NFIP policy. Kent properties in FEMA flood zones along the Green River corridor, including Riverview and areas near Frager Road South, may need both types of coverage.
How long does a burst pipe insurance claim take in Kent, WA?
Most burst pipe claims in Kent are acknowledged within a few days and adjuster inspections are typically scheduled within one to two weeks of the loss. Total claim resolution, from initial call through final payment, usually runs four to twelve weeks depending on the scope, the carrier, and whether any scope disputes arise. We move the documentation side as fast as possible to reduce your waiting time.
What if my insurance company only wants to pay for part of the damage?
This is common and worth addressing immediately. We provide additional documentation upon request, including thermal imaging reports, third-party moisture verification, and industry standard references. If the gap is significant, we can refer you to a Washington State licensed public adjuster who works on contingency and specializes in residential water damage claims.
How is direct insurance billing handled?
Call us any time. We will walk you through the claims process before a contractor's truck even rolls.
Call (831) 230-1431Related Kent burst pipe pages
Does my Washington policy cap what it pays for water damage?
Direct answer: it might, and most homeowners never check. The Washington Office of the Insurance Commissioner has warned consumers that some home policies sold in this state carry an optional water damage sublimit — a separate, much lower cap that applies only to water losses. The OIC's example: a policy with a $500,000 dwelling limit but only a $10,000 sublimit for water damage. Five insurers writing in Washington had considered offering policies structured this way when the alert was issued.
That $10,000 matters here, because the OIC states the sublimit covers exactly the events this site deals with — a pipe breaking and releasing water in a house, whether from a sink, toilet, water heater, dishwasher, or a frozen pipe. A multi-room Kent burst pipe with drying and reconstruction runs $8,000 to $18,000. Against a full dwelling limit that is routine; against a $10,000 sublimit the homeowner pays the rest.
Take five minutes before you ever need it: open your declarations page and look for a line reading "water damage limit," "water sublimit," or a coverage schedule where a water entry has a different number from the dwelling limit. If the numbers differ, that is your real ceiling. Your agent can usually remove or raise the sublimit at renewal, and the premium difference is small compared to the exposure. If an insurer applies a sublimit you were never told about, the OIC consumer hotline is 800-562-6900.
Burst Pipe in Kent Right Now?
Your call routes directly to a licensed local contractor. On-site in 60 minutes across all Kent ZIP codes.
(831) 230-14311819 Central Ave S, Kent, WA 98032 · Serving 98030 · 98031 · 98032 · 98042 · Work performed by licensed, insured, IICRC-certified contractors
Sources referenced on this page
- Washington OIC — watch out for policies that limit your water damage coverage (sublimits)
- Washington OIC — leaks, water damage and mold coverage
- Washington OIC — file a complaint against an insurer
- FEMA — NFIP
Last updated: October 20, 2026. Reviewed against the City of Kent Water Quality Report and IICRC S500 standard.